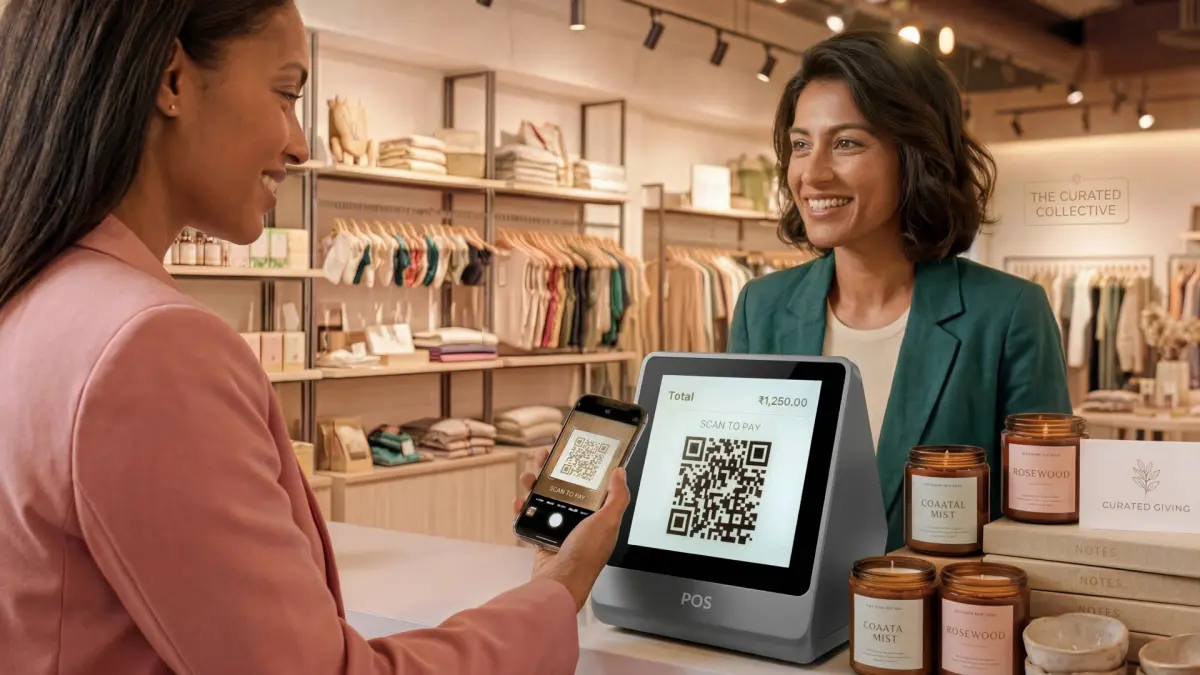
India processes more than 24 billion UPI transactions every month. NPCI data shows 24.07 billion transactions worth ₹29.37 lakh crore in September 2026. Many of these happen at physical retail stores like billing counters and checkout desks. Customers come ready with their phones and UPI apps, expecting a quick and smooth checkout.
But for many retailers, the checkout process is slower and more complicated because UPI payments are accepted but not integrated into their systems.
Two things changed in 2026 that this guide covers: NPCI phased out the UPI collect flow for most merchant payments from 28 February 2026, and a new merchant fee (MDR) on UPI payments above ₹2,000 starts on 15 October 2026.
This guide explains what UPI integration in a POS system means, why it is important and how retailers can set it up properly.
What is UPI payment integration in POS?
A Point of Sale (POS) system is a combination of hardware and software that processes sales transactions. The hardware, like a POS machine, card reader, or barcode scanner, handles the physical side of the transaction. The software manages everything behind the counter: billing, inventory tracking and sales reporting.
Unified Payments Interface (UPI) is a real-time payment system run by the National Payments Corporation of India (NPCI) that allows instant bank transfers using a Virtual Payment Address (VPA), QR code or mobile number.
Retailers don't deal with NPCI directly. You accept UPI through a bank or a payment aggregator or gateway, and they apply NPCI's rules to your payments.
UPI POS integration for retail means connecting the POS system directly with the UPI payment system. This lets payment requests, confirmations and records move automatically between the POS, payment gateway, and banks without manual work.
Accepting UPI vs. integrating UPI: Understanding the difference
Accepting UPI means having a static QR code at the store that customers scan to pay. The payment happens outside the POS system and someone must manually check and record it later.
Integrating UPI means the POS creates a payment request for each sale, gets real-time payment confirmation, and automatically updates sales, inventory and reports.
Accepting UPI is a temporary fix. Integrating UPI is the right way to build a reliable payment system.
Why retailers need proper UPI integration
Manual errors: Without automatic recording, staff must match payments manually, which leads to mistakes as transactions increase.
Checkout delays: Checking payments manually slows down the checkout, especially during busy times.
Incomplete data: Payments outside the POS do not appear in reports, causing unreliable sales and inventory data.
Refund problems: Without linked transactions, refunds and disputes take longer and are harder to manage.
No audit trail: Integrated systems keep a clear record of payments; unintegrated ones do not, which makes audits and tax checks harder.
How to integrate UPI in POS system
The cashier adds items and creates a bill in the POS
The customer chooses UPI as the payment method
The POS sends a payment request to the payment gateway
The gateway creates a dynamic QR code for the exact amount or, on a mobile device, a UPI intent link that opens the customer's UPI app
The customer scans the QR or approves in their UPI app and enters their UPI PIN
The bank processes the payment and sends confirmation to the gateway
The gateway sends confirmation to the POS, either as a status update or in answer to the POS checking the status
The POS marks the bill paid, updates inventory and prints a receipt automatically
The transaction finishes without manual checks or extra record-keeping.
What can happen between those steps. A payment moves through states, and your POS and staff should handle each one:
State | What it means | What the POS should do | What staff should do |
|---|
Created | The bill is ready and a QR or intent link is generated | Show the QR for the exact amount and start a timer | Wait, and don't change the cart |
Pending | The customer has scanned or approved, but the bank hasn't confirmed | Keep the bill open and check the status | Don't ask the customer to pay again |
Success | The bank confirmed the payment | Mark the bill paid, print the receipt, reduce stock | Hand over the goods |
Failed | The payment was declined (wrong PIN, low balance, bank error) | Show the reason and allow a retry or another payment mode | Offer a retry or another mode |
Expired | The QR timed out without payment | Cancel that attempt | Create a new QR only after the old one is cancelled |
Unknown | No final answer from the bank, for example after a timeout or a network drop | Keep checking, hold the bill and flag it for review | Check the status, and never mark it paid or charge again until confirmed |
Refund initiated, refunded or failed | Money is on its way back to the customer | Link it to the original bill and show its status | Don't hand back cash without recording it |
Duplicate | The customer paid the same bill twice | Flag it and refund the extra payment | Escalate to your manager |
The golden rule: mark a bill paid only on a confirmed status from the gateway, never on a screenshot of the customer's phone.
In Fynd: the POS payment API supports payment initiation for UPI and QR, payment polling, and status checks for single or bulk payments.
Step-by-Step guide to integrating UPI in your POS
Step 1: Evaluate your current POS system
Check if your POS supports:
Dynamic QR code for each sale
Real-time payment updates and clear payment states (pending, success, failed, expired)
Automatic transaction recording
Refunds through the system, linked to the original bill
If not, consider upgrading to a modern POS before adding UPI integration.
Step 2: Select a payment gateway
Choose a gateway that offers:
Support for popular UPI apps (GPay, PhonePe, Paytm, BHIM)
UPI intent and dynamic QR, since the collect flow is largely phased out (see "Types of UPI integration methods")
Fast settlement times
High success rates and reliability
Good API documentation for integration
Security certifications (PCI DSS, which applies to card payments)
Responsive merchant support
Questions to ask any gateway (use them to build your own comparison):
Question | Why it matters |
|---|
Is there a dynamic QR for each bill, and an intent flow for mobile devices? | These are the flows that remain after the collect phase-out |
How do I get a payment status: status updates, status checks, or both? | Your POS must never rely on a screenshot |
How are refunds made, and how long do they take in practice? | This affects customer trust and your cash flow |
When does money settle, and what is deducted before settlement? | You need to know the gross and net amounts |
How will you handle the new MDR from 15 October 2026, and do any of your own fees change? | It affects your margins on bills above ₹2,000 |
Can I use separate merchant IDs or QR codes for each store? | It makes store-wise reconciliation easier |
What reports and reference numbers do I get? | You need them to match POS bills to bank credits |
Which terminals and QR displays work with you? | It decides your hardware plan |
How Fynd POS maps to this, from Fynd's documentation:
Provider | Role in Fynd POS | Source |
|---|
Razorpay | POS payment modes are labelled by provider, with "QR powered by Razorpay" as an example. Fynd's Assisted Merchant Account lets you accept payments through Razorpay without setting up your own account, and Fynd's guide says charges can be lower than with your own merchant account because of negotiated rates. You can also use your own account | Fynd payment API, Fynd payments setup |
Juspay | "CARD powered by Juspay" is an example POS payment mode | Fynd payment API |
PayU | Listed as the "PayU India Extension" aggregator option | Fynd platform payment API |
Pine Labs | A910 card terminal for card and dynamic QR payments, cloud-integrated on Android and iOS | Fynd POS and mPOS documentation |
What UPI costs in 2026
"Zero MDR" no longer covers every payment. From 15 October 2026, an NPCI framework applies a merchant discount rate (MDR) to specified person-to-merchant UPI payments. This is summarised from NPCI's FAQs dated 15 September 2026:
Payment | MDR | Example |
|---|
UPI payments up to ₹2,000 | None | ₹2,000: ₹0 |
Specified payments above ₹2,000 | 0.4% | ₹3,000: ₹12. ₹50,000: ₹200 |
Payments of ₹75,000 and above | Capped at ₹300 | ₹75,000: ₹300 |
Small merchants receiving up to ₹1 lakh a month through UPI QR (the P2PM category) | None, with no GST registration needed to qualify | |
Credit-linked UPI (RuPay credit on UPI, credit lines) | Not covered by this MDR | |
Railways, telecom, insurance, fuel and other notified categories | A flat ₹5 for payments above ₹2,000 | |
Merchants can't pass the MDR on to customers, and your existing QR codes keep working. NPCI says payments up to ₹2,000 are more than 95% of merchant UPI volume. Bills above ₹2,000 are the ones in scope, so check your own average bill value. For comparison, the same coverage notes that credit card MDRs typically range from 1.5% to 2.5%, with debit card MDR capped up to 0.90%.
Other costs to plan for:
Gateway or aggregator fees, set by your contract. Ask whether anything changes on 15 October.
Hardware, such as a QR display, soundbox or card terminal.
Integration and testing time, which is a one-off.
Staff time on exceptions and reconciliation, which is ongoing.
Step 3: Complete merchant onboarding and KYC
Submit required documents like GST certificate, bank details, PAN, and identity proofs. The time this takes varies by gateway and bank, so ask for an estimate in writing.
Step 4: Obtain your merchant UPI ID (VPA)
The payment gateway or bank gives you a Virtual Payment Address (VPA) that links to your bank account and is used in payment requests. If you run several stores, ask whether each store can have its own merchant ID or QR identity. It makes store-wise reconciliation much easier.
Step 5: Integrate the gateway with your POS
Integration can be:
Native: Built-in connectors in modern POS systems
Plugin-based: Add-ons that connect POS to the gateway
API-based: Custom integration needing developers
Work with your gateway's team to ensure smooth setup.
In Fynd: the payment API lists Razorpay and Juspay as aggregators, with PayU India and a checkout provider available as extensions.
Step 6: Set up payment hardware
Depending on your store, you may need:
A customer-facing screen showing QR codes
All-in-one POS terminals
Audio devices to confirm payments
Mobile POS devices for assisted selling
A card terminal, such as the Pine Labs A910 that Fynd lists as integrated
Step 7: Test all transaction scenarios
Use the gateway's test environment to check:
Successful payments via different UPI apps
Handling of payment failures
A pending payment that later succeeds, and one that later fails
A QR that expires, and a customer who scans an old QR
The same bill paid twice
A wrong amount
Partial or split payments
Refund processing, full and partial
Accurate transaction records
Internet interruptions, including what the cashier sees when the connection drops after the customer has paid
Testing prevents issues at live checkouts.
Step 8: Train store staff
Make sure staff can:
Start UPI payments from the POS
Recognise and handle failed, pending and unknown payments
Check a payment's status, and never rely on a screenshot
Process refunds
Contact support if needed
Provide guides and practice sessions before going live.
Step 9: Monitor and reconcile post go-live
After launch, regularly:
Check daily settlement reports
Compare gateway and POS records
Set alerts for payment issues
Assign someone to fix discrepancies
Early monitoring helps catch problems quickly.
A simple three-way match. For each store and day, match:
POS bills paid by UPI,
Gateway transactions, using the transaction ID and UPI reference number, and
Bank settlement credits, using the settlement reference.
Common breaks and what to do:
Break | Likely cause | Action |
|---|
Paid at the bank, but the POS shows pending | The confirmation never reached the POS | Check the status, then update the bill |
POS shows paid, but there is no settlement yet | Settlement timing or a hold | Check the settlement cycle with your gateway |
Settlement is lower than POS sales | Fees, MDR or refunds deducted before settlement | Reconcile gross to net, and keep the deduction detail |
Two payments for one bill | A duplicate scan | Refund the extra one |
Refund missing | It was initiated but not completed | Follow it up with the gateway |
Payment under the wrong store | The wrong merchant or QR mapping | Fix the mapping |
From 15 October, check how your gateway shows any MDR on bills above ₹2,000, so you can reconcile gross sales to net settlement.
In Fynd: the POS includes cash register management with end-of-day reconciliation, and the payment API offers bulk status checks.
Types of UPI integration methods
Three ways to accept UPI payments at POS:
Dynamic QR code POS: POS creates a unique QR code for each sale with the exact amount. Customers scan and pay. This is the main method at a counter.
UPI intent: The POS sends a link that opens the customer's UPI app on the same device. This suits mobile POS, self-checkout and any payment made on the customer's own phone.
UPI collect request: The POS sends a payment request to the customer's UPI ID for approval. NPCI deprecated this flow from 28 February 2026, so customers can no longer pay by manually entering a UPI ID or mobile number. It remains available only for a few cases, such as IPO and secondary market payments, iOS app and mobile web payments, UPI mandates and eRupi vouchers. New integrations should use dynamic QR or intent.
Dynamic QR and intent give real-time confirmation and automatic recording when integrated properly. A static QR code does not.
Key compliance and security requirements
Different parties carry different responsibilities. Here is how they divide:
Area | What applies | Who carries it |
|---|
UPI rules (NPCI) | Flows, limits and fees such as the collect phase-out and the MDR framework | Banks and payment providers apply them. You feel them through your gateway |
PCI DSS | A security standard for card data. It applies to card payments and card terminals, not to UPI itself | Your gateway and terminal provider certify. Your POS must not store card data |
Encryption | Payment data should be encrypted when it moves between systems | Your POS, gateway and terminal providers |
Tokenisation | Replaces card details with tokens. It applies to cards, not to UPI | Card networks, banks and gateways |
Transaction limits | Limits vary by category and bank. NPCI raised limits for selected verified categories, up to ₹10 lakh a day, from 15 September 2025 | Check yours with your bank |
GST and e-invoicing | Your POS should create GST-compliant invoices and support e-invoicing if it applies to you | You, with your chartered accountant. This is general information, not tax advice |
How Fynd POS supports UPI-ready retail operations
Fynd POS is a cloud POS with UPI support, built for modern retail and running on Android, iOS or any browser without proprietary hardware. You'll still need a printer, scanner and card terminal where you want them.
The payment setup, from Fynd's documentation:
Supports cash, card, UPI, payment links and net banking, plus card and dynamic QR payments through a card terminal
POS payment modes are labelled by provider, for example QR powered by Razorpay and card powered by Juspay
An Assisted Merchant Account for Razorpay, so you can start without your own account, or you can use your own
PayU India and a checkout provider available as aggregator extensions
A Pine Labs A910 terminal for card and dynamic QR payments at the counter
A dynamic UPI QR for every transaction, mapped to the exact bill amount
Payment confirmation reflected in the POS through payment status checks
Full transaction records, GST-compliant billing and automatic inventory updates
Cash register management with end-of-day reconciliation
Payment providers activated by business unit (storefront or POS) and device
See how Fynd can help your business
Talk to our team to modernise your retail and ecommerce operations.
Book a free demo